Tax credits for alternative fuel vehicles used to feel like a secret menu item at a restaurant: everyone heard about them, nobody was completely sure what qualified, and the fine print arrived wearing a tiny IRS hat. The good news is that the rules can be understood. The less-fun news is that the federal clean vehicle credit landscape changed dramatically after 2025, so old advice floating around the internet may now be about as useful as a gas receipt in a bicycle shop.
For many years, U.S. buyers could lower the cost of electric vehicles, plug-in hybrids, fuel cell vehicles, and certain commercial clean vehicles through federal tax credits. Under the Inflation Reduction Act, those credits became more targeted, with rules tied to income, vehicle price, battery sourcing, North American assembly, dealer reporting, and business use. Then the One Big Beautiful Bill changed the timeline. As of 2026, the main federal purchase credits for new, used, and commercial clean vehicles are generally no longer available for vehicles acquired after September 30, 2025. However, the Alternative Fuel Vehicle Refueling Property Credit, often discussed as the EV charger tax credit, can still apply to eligible property placed in service before July 1, 2026.
In plain English: the vehicle-buying party is mostly over at the federal level, but the charger-and-refueling-equipment party still has a few snacks left on the table. Let’s break down what counted, what changed, and how drivers, homeowners, businesses, and fleet managers can avoid expensive misunderstandings.
What Are Alternative Fuel Vehicles?
An alternative fuel vehicle is a vehicle that runs partly or entirely on a fuel other than conventional gasoline or diesel. In tax-credit discussions, the most common examples include battery electric vehicles, plug-in hybrid electric vehicles, hydrogen fuel cell vehicles, and some vehicles powered by fuels such as natural gas, propane, E85, or qualifying biodiesel blends. The term sounds broad, but tax law is picky. A vehicle being “green-ish” does not automatically mean it earns a credit. The IRS does not hand out money because a dashboard has a leaf icon.
For federal clean vehicle credits, qualifying vehicles historically had to meet specific technical and legal requirements. New clean vehicles generally needed enough battery capacity, a qualifying manufacturer, final assembly in North America, and compliance with battery component and critical mineral rules. Used clean vehicles had their own requirements, including a maximum sale price and model-year limits. Commercial clean vehicles followed a separate formula based on vehicle weight, basis, powertrain type, and incremental cost compared with a similar gasoline or diesel vehicle.
The Big 2026 Update: Federal Vehicle Purchase Credits Have Mostly Ended
The most important fact for readers today is simple: the federal New Clean Vehicle Credit, Previously-Owned Clean Vehicle Credit, and Qualified Commercial Clean Vehicle Credit are not available for vehicles acquired after September 30, 2025. That does not mean everyone who bought before that date is out of luck. If a taxpayer entered into a written binding contract and made a payment on or before September 30, 2025, the vehicle may still be eligible when placed in service later, assuming every other requirement is satisfied.
This “acquired by the deadline” rule matters because buying a vehicle and taking possession of it are not always the same thing. For example, someone may have signed a binding agreement and paid a deposit before the deadline, but the vehicle arrived weeks later. In that case, the taxpayer may still be able to claim the credit when the vehicle is placed in service, which generally means when the buyer takes possession. The key is documentation. A handshake, a hopeful text message, or “the salesperson said it should be fine” is not a tax strategy. Keep the contract, proof of payment, seller report, VIN records, and any dealer-provided time-of-sale documentation.
New Clean Vehicle Credit: What It Looked Like Before Expiration
Before the deadline, the New Clean Vehicle Credit could be worth up to $7,500 for eligible electric vehicles and fuel cell vehicles. The credit was split into two possible $3,750 pieces: one tied to critical minerals and another tied to battery components. If a vehicle met both requirements, it could qualify for the full amount. If it met only one, the credit could be reduced. If it met neither, the credit disappeared faster than free donuts in an office kitchen.
There were also income limits. For new clean vehicles, modified adjusted gross income generally could not exceed $300,000 for married couples filing jointly, $225,000 for heads of household, or $150,000 for other filers. The taxpayer could use modified AGI from the year of delivery or the previous year, whichever was lower. This rule gave some buyers flexibility, especially if their income changed from one year to the next.
Vehicle price limits mattered too. The manufacturer’s suggested retail price could not exceed $80,000 for vans, SUVs, and pickup trucks, or $55,000 for other vehicles. That MSRP limit included manufacturer-installed options and trim, but not destination fees. So yes, a few thousand dollars in factory upgrades could make the difference between “eligible” and “nice car, no credit.”
Used Clean Vehicle Credit: Smaller Credit, Big Fine Print
The Previously-Owned Clean Vehicle Credit was designed to help buyers who wanted a used EV or fuel cell vehicle instead of a brand-new one. Before expiration, the credit was worth up to $4,000, calculated as 30% of the vehicle’s sale price, with the credit capped at $4,000. The vehicle generally had to be purchased from a dealer for $25,000 or less, and the model year had to be at least two years earlier than the calendar year of purchase.
The used vehicle credit also came with income limits that were lower than the new vehicle credit. Buyers typically had to stay under $150,000 for married filing jointly, $112,500 for heads of household, or $75,000 for other filers. The buyer also had to be an individual, not a business, and the purchase had to meet first-transfer rules after August 16, 2022. Translation: not every used EV on a dealer lot qualified, even if the price looked right and the battery was humming happily.
One practical example: suppose a buyer acquired a qualifying used plug-in hybrid from a licensed dealer on September 20, 2025, for $20,000. If the vehicle met all IRS requirements and the buyer’s income was under the limit, the potential credit could be $4,000 because 30% of $20,000 is $6,000, but the credit was capped at $4,000. If the same vehicle was acquired on October 2, 2025, the federal used clean vehicle credit would generally not be available.
Commercial Clean Vehicle Credit: Useful for Fleets, but Also Time-Limited
The Qualified Commercial Clean Vehicle Credit was especially important for businesses, nonprofits, local governments, and fleets. Before expiration, it could be worth up to $7,500 for vehicles under 14,000 pounds gross vehicle weight rating, and up to $40,000 for heavier vehicles such as electric buses, box trucks, or semi-trucks. The credit calculation generally used the lesser of a percentage of the vehicle’s basis or the incremental cost compared with a similar gasoline or diesel vehicle.
For fully electric or fuel cell commercial vehicles, the percentage could be 30% of basis. For plug-in hybrid commercial vehicles, the percentage was generally 15%. Commercial credits were not subject to the same individual income limits as consumer credits, which made them attractive to fleet operators. However, the vehicle had to be used for business, not resale, and primarily in the United States. Businesses also had to consider depreciation, basis reduction, and general business credit rules.
For a delivery company, the old credit could make a real difference. Imagine a small bakery replacing two aging gasoline vans with electric delivery vans acquired before September 30, 2025. If the vans qualified, the credit could help offset the higher upfront purchase price. The bakery might also save on fuel and maintenance over time. Of course, the bakery would still need to coordinate with a tax professional, because frosting cupcakes and calculating basis are very different skill sets.
Point-of-Sale Transfers: The Discount That Was Not Exactly a Discount
Starting in 2024, eligible buyers of new or used clean vehicles could transfer the federal clean vehicle credit to a registered dealer at the time of sale. Instead of waiting until tax filing season, the buyer could receive an immediate financial benefit, such as a reduced purchase price, partial payment, or down payment. This was one of the most consumer-friendly features of the program because it made the credit feel less like homework and more like money off the car.
However, the buyer still had responsibilities. Even if the credit was transferred to the dealer, the taxpayer still had to file Form 8936 and Schedule A with the federal tax return for the year the vehicle was placed in service. If the buyer later turned out not to qualify, perhaps because income exceeded the limit, repayment could be required. The dealer also had to be registered and had to submit a time-of-sale report through IRS Energy Credits Online. Without a successful seller report, eligibility could fall apart.
The Alternative Fuel Vehicle Refueling Property Credit Still Matters
While the main vehicle purchase credits ended for vehicles acquired after September 30, 2025, the Alternative Fuel Vehicle Refueling Property Credit remains highly relevant in 2026. This credit applies to qualified refueling or recharging property placed in service from January 1, 2023, through June 30, 2026. It can help homeowners, businesses, and certain tax-exempt entities offset the cost of installing eligible equipment.
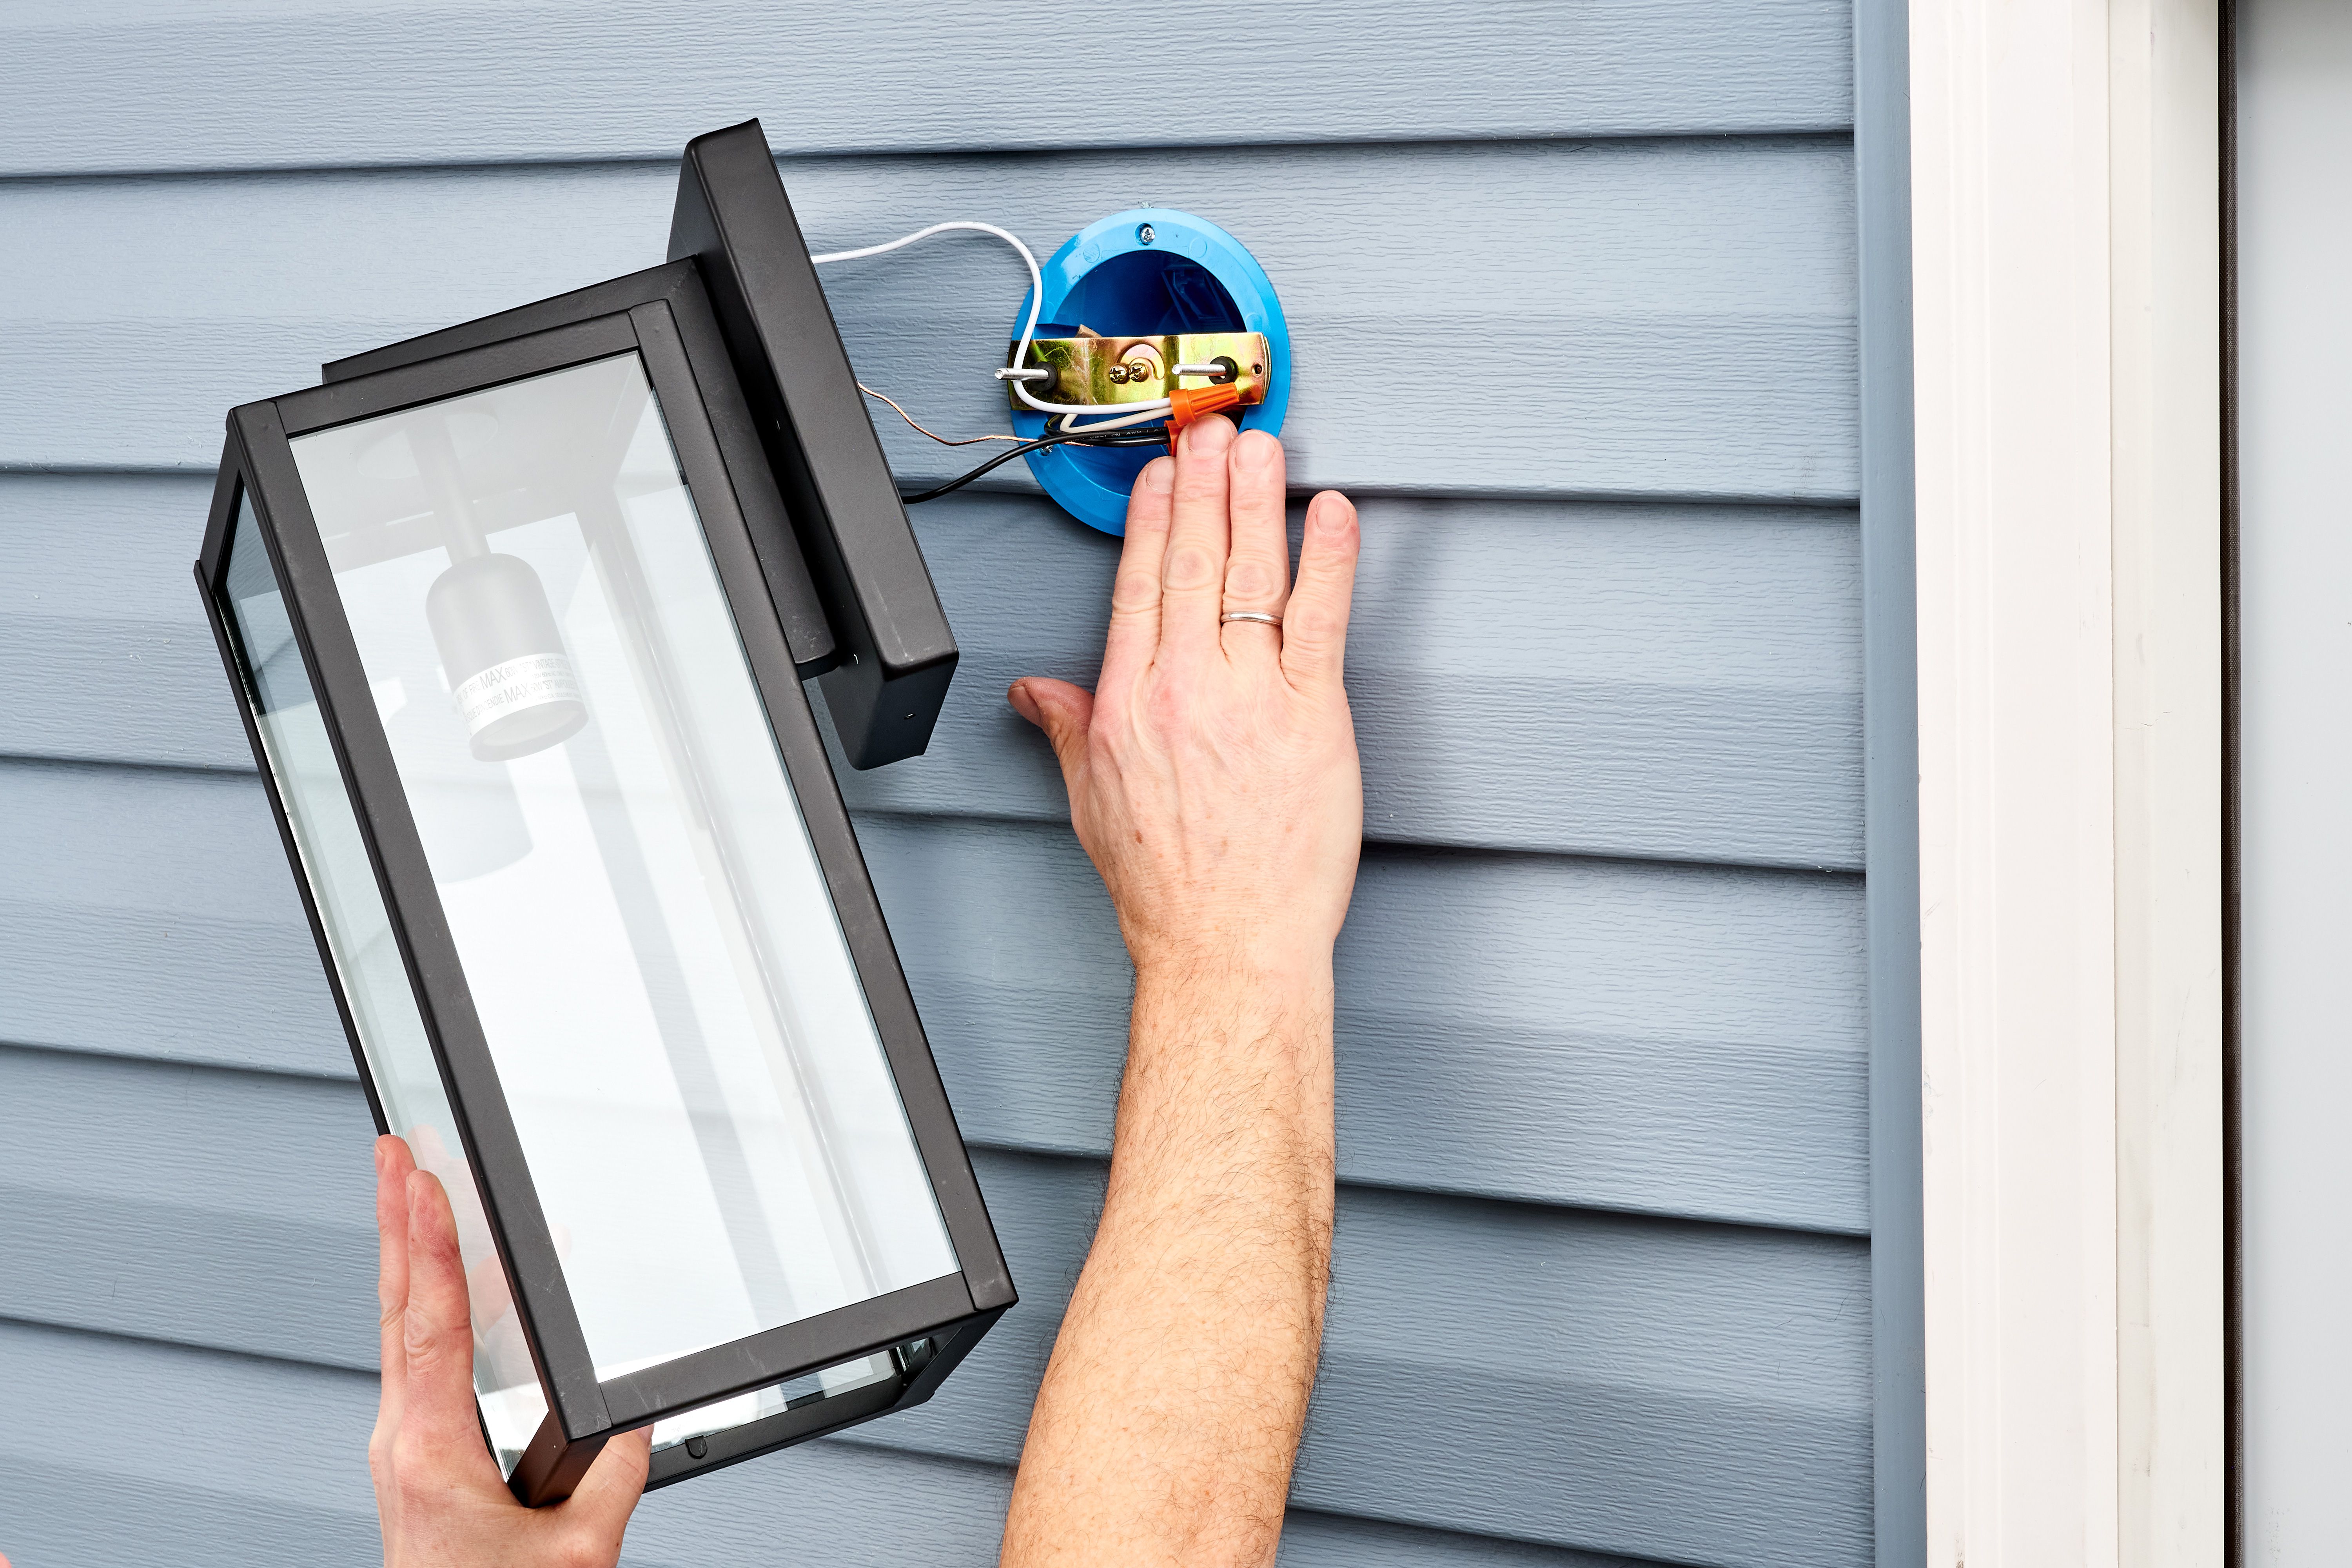
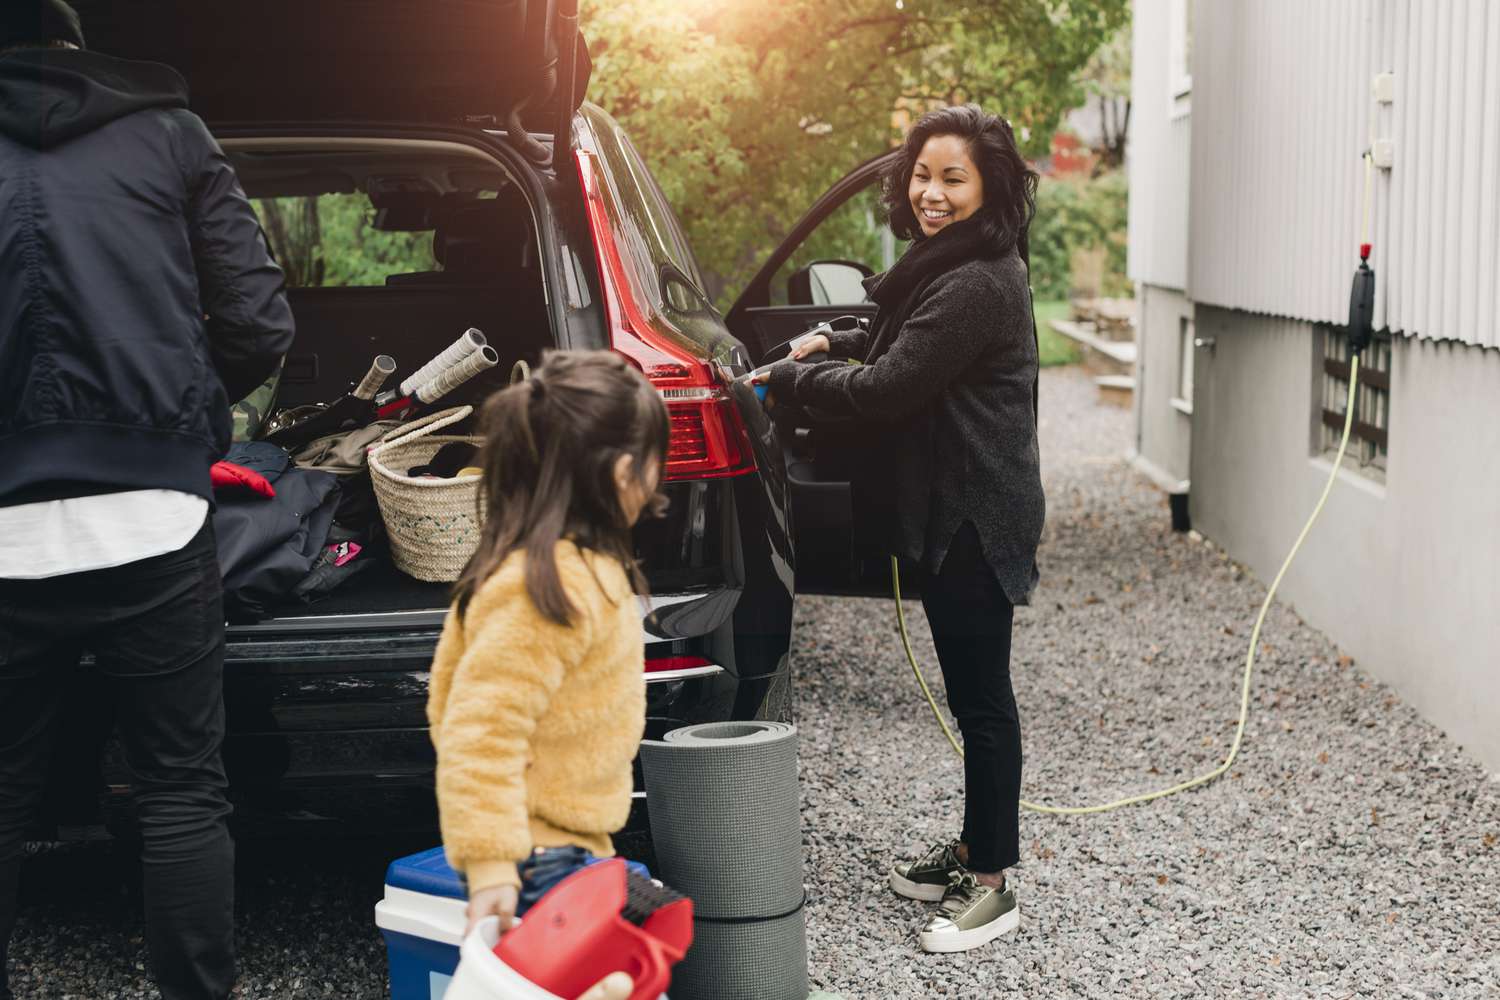
For individuals installing qualified equipment at a principal residence, the credit equals 30% of the cost, up to $1,000 per item. In the EV world, that often means a home charging port and certain directly related installation costs. The property must be placed in service before July 1, 2026. “Placed in service” means installed and ready for use, not merely ordered, scheduled, or sitting in a box in the garage next to holiday decorations and mysterious extension cords.
Location matters. To qualify, the property generally must be installed in an eligible census tract, such as a low-income community census tract or a non-urban census tract. This requirement surprises many homeowners. Buying a charger is not enough. Installing it at the right location is part of the eligibility test. Homeowners should check eligibility before committing money, especially if the credit is a major part of the project budget.
Business Charging and Refueling Equipment
Businesses may also claim the Alternative Fuel Vehicle Refueling Property Credit for eligible equipment, including EV charging stations and certain equipment for hydrogen, natural gas, propane, E85, or biodiesel blends of at least 20%. For depreciable property, the base credit is generally 6% of cost, with a maximum of $100,000 per single item of property. If prevailing wage and apprenticeship requirements are met, the credit can rise to 30%.
This is a significant opportunity for workplaces, apartment complexes, retail centers, hotels, delivery fleets, and public charging operators. A business installing multiple charging ports may be looking at a credit per port or per single item of qualifying property, depending on the equipment. Labor and essential installation components may also be part of the eligible cost calculation. As always, the business must own the property and meet location requirements.
For example, a rural grocery store installing two Level 2 charging ports for customers could potentially qualify if the site is in an eligible census tract and the property is placed in service before the deadline. The credit would not just support EV drivers; it could also encourage shoppers to stay longer. Nothing says “retail strategy” quite like letting someone charge their car while they accidentally buy three kinds of salsa.
State, Local, and Utility Incentives Can Still Save Money
Federal credits get most of the attention, but they are not the whole story. Many state governments, local agencies, and electric utilities offer incentives for EV purchases, home chargers, fleet electrification, off-peak charging, or make-ready electrical work. These programs change frequently and vary by ZIP code, utility territory, income level, and vehicle type.
Some states offer rebates for new or used EVs. Others focus on charging infrastructure, especially for multifamily housing, workplaces, disadvantaged communities, or rural corridors. Utilities may provide rebates for Level 2 chargers, special time-of-use electricity rates, or incentives for smart chargers that can shift charging away from peak demand hours. The smartest move is to check federal, state, local, and utility programs before signing a purchase contract or hiring an electrician.
Common Mistakes to Avoid
Assuming Old Credit Rules Still Apply
Many articles, videos, and dealership pages were written before the September 30, 2025 deadline. If a page says “available through 2032” without mentioning the later law change, treat it carefully. Tax incentives are not museum exhibits; they move.
Forgetting the Dealer Report
For clean vehicle credits tied to pre-deadline purchases, dealer reporting remains crucial. Buyers should keep the time-of-sale report and confirm that the dealer submitted required information successfully. A qualifying vehicle without proper paperwork can become a very expensive lesson in administrative drama.
Ignoring Income Limits
Income limits were not optional. A buyer who transferred a credit at the dealership but later exceeded the modified AGI limit could have to repay the credit. That is not a fun surprise at tax time.
Installing Charging Equipment Too Late
For the refueling property credit, equipment must be placed in service before July 1, 2026. Scheduling an electrician for June 30 and hoping everything goes perfectly is bold. Bold is great for hot sauce, less great for tax deadlines.
Practical Checklist Before Claiming a Credit
Before claiming any alternative fuel vehicle-related tax credit, collect the basic evidence. For vehicle credits, keep the purchase agreement, proof of payment, VIN, window sticker if relevant, time-of-sale report, dealer confirmation, and delivery records. For charger or refueling property credits, keep invoices, proof of payment, installation records, permits if applicable, equipment specifications, photos of completed installation, and documentation showing when the property was ready for use.
Next, match the credit to the correct tax form. Clean vehicle credits generally use Form 8936 and Schedule A. Refueling property credits use the applicable IRS forms and instructions for Section 30C property. Businesses may also need to coordinate with general business credit forms, depreciation schedules, and accounting records. When the numbers are large, professional tax advice is worth it. The IRS is not impressed by “I saw a TikTok about it” as a filing position.
Real-World Experiences: What Buyers and Businesses Often Learn the Hard Way
People shopping for alternative fuel vehicles often start with the exciting part: range, horsepower, charging speed, monthly payment, and whether the car makes them feel like they live slightly in the future. Then the tax-credit conversation begins, and suddenly everyone is discussing modified adjusted gross income at a dealership desk under fluorescent lighting. The experience can be confusing, but a few patterns show up again and again.
First, timing matters more than many buyers expect. A buyer who acquired a qualifying vehicle before September 30, 2025 may still have a path to the credit, but someone who waited until after the deadline generally does not. That difference can be thousands of dollars. The lesson is simple: when a tax credit has a deadline, “almost” is not a filing status. Buyers should never assume that a reservation, online order, or casual deposit automatically counts as acquiring a vehicle. The safest approach is to ask for a written binding contract, proof of payment, and a clear explanation of when the vehicle will be placed in service.
Second, dealerships vary widely in tax-credit knowledge. Some dealers understand the process, submit reports promptly, and hand buyers clean documentation. Others act as if Form 8936 just landed from another planet. Buyers who successfully navigated the credit often asked specific questions before signing: Are you registered with IRS Energy Credits Online? Will I receive the time-of-sale report today? Has the IRS accepted the submission? What credit amount is shown? Is the VIN correct? These questions may not sound glamorous, but neither is losing a credit because one digit was wrong.
Third, charger installation can become its own adventure. Homeowners may budget for the charger but forget the electrical panel, wiring distance, permits, trenching, or labor. A simple installation in a garage might be straightforward, while an older home with a full electrical panel may need upgrades before a Level 2 charger can be safely installed. For the Alternative Fuel Vehicle Refueling Property Credit, the experience improves when homeowners confirm census tract eligibility first, schedule installation early, and save every invoice. A charger installed and ready for use before the deadline is much better than a charger sitting unopened in a delivery box, silently judging everyone.
Businesses often learn a different lesson: infrastructure planning matters as much as vehicle selection. A company can buy electric vans, but if the charging setup is too slow, poorly located, or installed after the credit deadline, daily operations may suffer. Fleet managers usually get better results by planning vehicle routes, dwell time, charger capacity, utility upgrades, and employee responsibilities before buying vehicles. The tax credit can reduce cost, but it cannot fix a charging plan held together with optimism and a spreadsheet named “final-final-v7.”
The best experience comes from treating tax credits as one part of the total ownership decision. Fuel savings, maintenance, insurance, resale value, electricity rates, charging convenience, warranty coverage, and available state incentives all matter. A credit can make a good decision better, but it should not turn a poor-fit vehicle into a smart purchase. In other words, do not buy a vehicle only because the tax math looks shiny. Buy it because it fits your life, your budget, your commute, or your businessand then use every legitimate incentive available to make the deal sweeter.
Conclusion
Tax credits for alternative fuel vehicles have helped millions of Americans consider cleaner transportation, but the rules have changed. As of 2026, the federal credits for buying new, used, and commercial clean vehicles are largely limited to vehicles acquired on or before September 30, 2025, subject to strict eligibility and documentation rules. The strongest remaining federal opportunity is the Alternative Fuel Vehicle Refueling Property Credit, which may help offset the cost of qualified EV chargers and other refueling equipment placed in service before July 1, 2026.
The winning strategy is not guessing. Check dates, confirm eligibility, save documents, verify dealer reporting, and look for state, local, and utility incentives. Clean transportation can still make financial sense, especially when lower operating costs and charging convenience enter the picture. Just remember: in the world of tax credits, the fine print is not fine decoration. It is the steering wheel.
Note: This article is for general educational purposes and should not be treated as personal tax advice. Tax rules can change, and individual eligibility depends on income, timing, vehicle details, location, documentation, and filing circumstances.