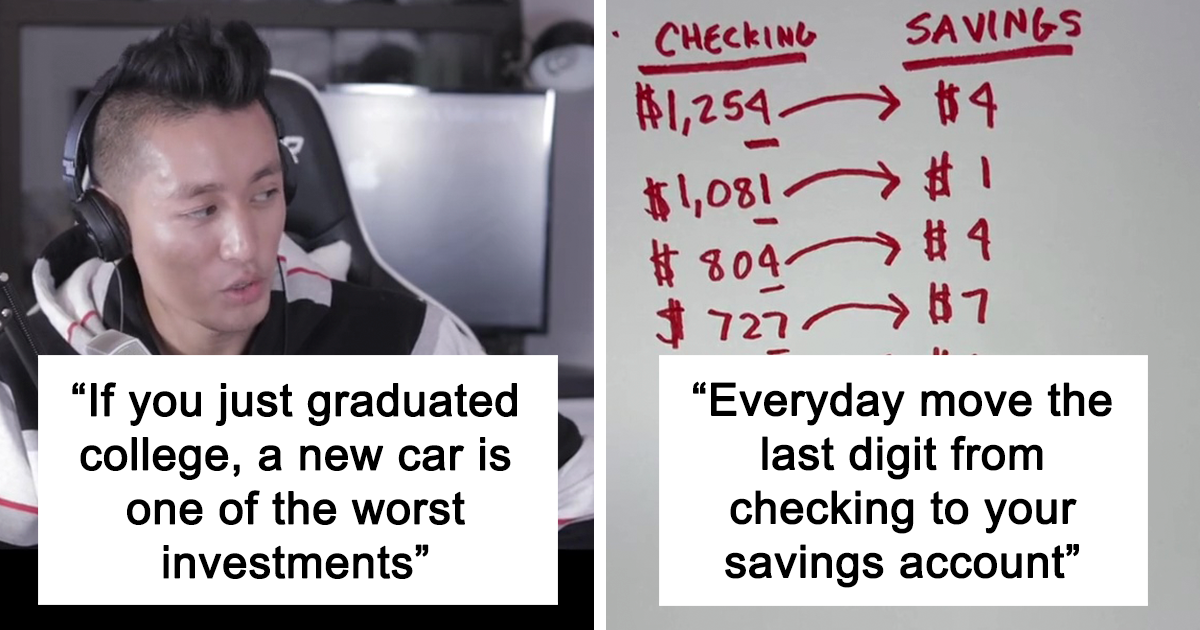
School taught us the Pythagorean theorem, the parts of a frog, and how to panic quietly during group projects. What it did not teach most people was how to read a pay stub, avoid lifestyle inflation, spot a financial scam wearing a friendly smile, or understand why one tiny fee can quietly nibble away at your future wealth like a raccoon in a snack pantry.
That is partly why money advice has exploded on TikTok. People want quick, practical answers to questions that matter in real life: How much should I save? Why is my paycheck smaller than expected? Is a credit card evil, magical, or just misunderstood? And why does every “easy money” video feel like it was produced by someone standing next to a rented Lamborghini?
The good news is that some financial lessons shared by creators online are genuinely useful. The bad news is that social media is also where terrible advice, oversimplified hot takes, and outright scams go to party. So instead of blindly trusting every dancing spreadsheet wizard on your feed, this article pulls together 22 smart money lessons that actually hold up in the real world.
Think of this as the financial literacy class many people wish they had gotten before signing a lease, opening a credit card, or confidently saying, “I’ll just figure taxes out later.” Spoiler: Later usually arrives with paperwork.
Why These Financial Lessons Matter More Than Ever
Money stress rarely comes from one giant dramatic event. More often, it shows up through small, repeated mistakes: ignoring a budget, carrying expensive debt, paying only the minimum, skipping retirement contributions, or believing that “future me” will somehow become an organized accounting wizard. Future you deserves better.
Short-form content works because it cuts through the jargon. A 30-second video can remind you to build an emergency fund, check your credit report, or stop confusing investing with gambling. But the best money advice is not flashy. It is repeatable. It is boring in the most beautiful way. It is the kind of advice that does not get millions of likes because it is dramatic. It gets results because it is useful.
22 Money Lessons TikTok Keeps Repeating for a Reason
1. A budget is not a punishment. It is a permission slip.
One of the smartest lessons floating around financial TikTok is that budgeting is not about saying no to everything fun. It is about deciding where your money goes before it wanders off and joins a mysterious subscription cult. A good budget tells your dollars what job they have. Rent has a job. Groceries have a job. Savings has a job. Friday-night tacos can absolutely have a job too.
2. Pay yourself first, not whatever is left over.
If saving only happens after every bill, snack run, impulse purchase, and “little treat” moment, it often never happens at all. Many savvy creators repeat one simple idea: automate savings first. Even small transfers build momentum. The point is not to start big. The point is to start on purpose.
3. An emergency fund is not optional adult decor.
You do not build emergency savings because you are pessimistic. You build it because life loves plot twists. A car repair, dental bill, broken phone, surprise move, or temporary income loss can turn into expensive chaos when there is no cash cushion. Emergency savings buy breathing room, and breathing room is underrated.
4. “I can afford the payment” is not the same as “I can afford the purchase.”
This lesson deserves a standing ovation. Monthly payment thinking is how people end up trapped in expensive loans for things they were never truly comfortable buying. A lower monthly payment can hide a longer term, more interest, and a much bigger total cost. The price tag matters, but the full cost matters more.
5. Credit cards are tools, not free money.
Used wisely, a credit card can help with convenience, fraud protection, and credit-building. Used carelessly, it becomes a high-interest drama series with multiple seasons. Many creators get this right: if you cannot pay the balance responsibly, rewards points are not saving you. A free airport lounge is not worth carrying expensive debt like an emotional support backpack.
6. Paying only the minimum is a very expensive habit.
Minimum payments keep accounts current, but they can stretch repayment far longer than people expect. Interest keeps piling up while your balance shrinks at the speed of a sleepy turtle. Paying more than the minimum whenever possible is one of the fastest ways to lower interest costs and get your money back under your control.
7. Your credit report deserves more attention than your ex’s vacation photos.
Checking your credit report is not obsessive. It is responsible. Errors happen, identity theft happens, and outdated information can quietly hurt you when you apply for an apartment, loan, insurance, or even a job in some cases. Reviewing your report regularly helps you catch problems before they become expensive surprises.
8. Your credit score is important, but your cash flow is more important.
A lot of online advice treats the credit score like the main character. It is important, yes, but it is not the whole story. A great score does not magically fix overspending or lack of savings. A financially healthy life is built on cash flow, low toxic debt, consistent saving, and good habits. The score should support the plan, not become the entire personality.
9. Compound interest is either your best friend or your favorite villain.
This is one of the greatest money lessons nobody should have to discover by accident. Compound growth helps invested money grow over time, which is excellent news when you are saving and terrible news when expensive debt compounds against you. The earlier you start investing or saving, the more time does the heavy lifting.
10. Starting small is not embarrassing. Starting never is.
One reason people delay investing is because they think they need a giant pile of money to begin. They do not. Waiting for the “perfect time” is how years disappear. Many practical creators emphasize progress over performance. A small, consistent contribution beats a dramatic future plan that never leaves the notes app.
11. Diversification is the opposite of putting all your hopes in one shiny thing.
If your entire financial future depends on one stock, one coin, one friend’s “can’t miss” idea, or one app with a suspiciously aggressive font, you are not investing. You are taking concentrated risk. Diversification spreads money across assets so one bad outcome does not wreck everything. It is not glamorous. It is just smart.
12. Fees matter more than people think.
Investment fees can look tiny on paper and still do real damage over time. Small percentages sound harmless until they keep quietly taking bites out of returns year after year. Smart money creators often say the same thing: understand the cost of your account, your funds, and your advisor before assuming your money is working only for you.
13. Your employer match is part of your compensation.
If your workplace offers a retirement match and you ignore it, you may be leaving money on the table. That is not always possible to fix immediately, especially if cash flow is tight, but it is worth understanding. An employer match is not a bonus prize for future you. It is part of the value of the job you already have.
14. Taxes are not just an annual jump scare.
Many adults discover too late that taxes are not something that simply “happens” in April. Your withholding, gig work, side income, freelance income, and investments all affect what you owe. The smart lesson here is simple: review your setup early. A W-4, estimated payments, and basic recordkeeping are not glamorous, but neither is a surprise tax bill.
15. Read your pay stub. Yes, the whole thing.
That number hitting your bank account is not the whole story. A pay stub shows taxes withheld, deductions, retirement contributions, benefits, and other details that shape your real take-home pay. A surprising number of people do not understand why their net pay differs from their salary until they finally look closely and mutter, “Oh. Oh no. There are many lines here.”
16. Lifestyle inflation is sneaky because it feels deserved.
Getting a raise should improve your life. It should not automatically inflate every category of spending until you still feel broke at a higher income. Smart TikTok advice often reminds people to increase saving and investing when income rises instead of upgrading everything at once. Celebrate the raise, absolutely. Just do not let your expenses throw a parade you cannot sustain.
17. Not every “side hustle” is a good financial move.
Some side hustles build skills and income. Others mostly sell the fantasy of income while draining your time, attention, and sometimes your money. If an opportunity requires big upfront fees, overpromises fast returns, or sounds suspiciously like “pay us to learn how to make money,” that is not a hustle. That is a lesson wearing clown shoes.
18. If someone promises huge returns with little or no risk, run.
This advice belongs on a giant banner over the internet. Scam artists love urgency, screenshots, hype, and “secret systems.” They also love social proof that looks real but is not. Whether the pitch shows up in a DM, group chat, livestream, or comment section, guaranteed riches are usually a trap. Real investing involves risk, patience, and very little shouting.
19. Financial boundaries are real boundaries.
Lending money to friends or family without clear expectations can turn love into resentment faster than you can say “I thought you were paying me back on Friday.” Several money creators make this point well: it is okay to set limits, say no, or only lend what you can afford to lose. Boundaries are not cold. They are protective.
20. Insurance is boring until it saves you.
Few people go viral by whispering, “I compared policies and understood my deductible.” Yet insurance decisions matter. Health, auto, renters, homeowners, and disability coverage can prevent one emergency from becoming a long financial spiral. It is not exciting content, but it is deeply adult content, which is sometimes even more important.
21. Retirement is not just for older people.
One of the biggest mindset shifts online is the reminder that retirement planning starts long before retirement feels real. Even if you are in your twenties or thirties and still figuring out life, knowing what your future benefits may look like and contributing steadily can make an enormous difference. Retirement is less about age and more about preparation.
22. Financial literacy is less about knowing everything and more about asking better questions.
The most useful creators do not pretend money is easy. They teach people to ask smarter questions: What is the interest rate? What are the fees? What is the tax impact? Is this advice regulated, researched, or just confidently delivered by someone next to a ring light? Financial confidence grows when curiosity becomes a habit.
What Financial TikTok Gets Right and What It Gets Wrong
At its best, financial TikTok makes money conversations feel approachable. It encourages people to budget, save, invest early, check credit reports, and stop being intimidated by terms that were once explained only in dense brochures or by a man in a tie named Greg. That accessibility matters.
But there is a difference between simplified and oversimplified. A useful creator can explain compound interest in plain English. A reckless creator can make day trading look like a personality test with cash prizes. The smartest approach is to treat social media as a starting point, not a final authority. Let it inspire questions. Then verify the advice with trustworthy sources, official guidance, or qualified professionals when the stakes are high.
The Real Lesson School Missed
The biggest financial truth many people learn outside the classroom is this: money management is not about being naturally “good with money.” It is about habits. Repeated, imperfect, occasionally boring habits. Budgeting once will not save you. Saving once will not save you. Reading one personal finance book while drinking an iced coffee and feeling superior for 45 minutes will not save you either.
What works is consistency. Track your money. Save automatically. Avoid obvious scams. Review your credit. Understand your paycheck. Respect taxes. Keep debt from running the show. Invest patiently. Ask questions when you do not know something. That is financial literacy in real life. Less performance, more practice.
Conclusion
If 22 TikTok users sat down to build the personal finance class most adults actually needed, it probably would not be full of jargon, pie charts, or soul-crushing lectures. It would be practical. It would explain how money behaves in everyday life. It would warn you that easy money is rarely easy, that small fees are not as small as they look, and that your future financial stability is built one ordinary decision at a time.
And maybe that is the real reason these lessons resonate. They are not revolutionary because they are flashy. They are revolutionary because they are usable. They help people move from confusion to control. And in a world full of financial noise, control is a pretty great flex.
Extra Experiences: What These Lessons Look Like in Real Life
For many people, financial education does not arrive through a textbook. It arrives through embarrassment, trial and error, and one slightly panicked Google search at midnight. Someone gets their first full-time job, sees the paycheck, and wonders why the number is smaller than expected. Another person signs up for a credit card because the rewards sounded fun, only to realize months later that interest is not a cute little side detail. Someone else gets a raise, celebrates responsibly for about three days, and then accidentally upgrades their entire lifestyle until the raise disappears into nicer takeout, more subscriptions, and a couch that looked “investment-worthy” in the showroom.
That is why practical money advice feels so powerful when people share it online. It sounds like real life because it comes from real life. One person talks about finally building a small emergency fund and how it turned a car repair from a meltdown into an inconvenience. Another explains how checking their credit report helped them catch a mistake before applying for an apartment. Someone else admits they thought investing was only for rich people, then discovered that consistency mattered more than looking wealthy on the internet.
There is also a deeply human side to all of this. Money mistakes can carry shame, even when they are common. People feel silly for not understanding taxes, nervous about asking basic questions, or guilty about debt that built up during a hard season. But hearing others talk openly about those experiences can be incredibly useful. It replaces the lonely feeling of “I should already know this” with a healthier thought: “Okay, I can learn this now.”
Many of the best financial lessons are not dramatic breakthroughs. They are quiet mindset changes. A person stops viewing budgeting as restriction and starts seeing it as control. A couple decides to talk honestly about money before resentment builds. A recent graduate learns that buying something just because the monthly payment looks manageable is not the same as being able to afford it. A young worker enrolls in a retirement plan not because retirement feels close, but because future stability finally starts to feel personal.
And then there are the scam lessons, which are unfortunate but real. Plenty of people only learn to recognize financial fraud after almost falling for it. Maybe it was a suspicious investment pitch in a DM, a fake side hustle that required an upfront fee, or a social media account showing off unbelievable returns with the confidence of a movie villain in a blazer. Those experiences can be frustrating, but they also sharpen judgment. People learn to slow down, verify claims, and trust boring reality over flashy promises.
In the end, financial growth usually looks less like a viral success story and more like a series of calmer decisions. Paying attention. Reading the fine print. Asking better questions. Making fewer avoidable mistakes. Building a life where money supports your goals instead of constantly interrupting them. That kind of progress may never trend, but it is the kind that changes everything.