Money has a funny way of acting simple until it is not. Saving a little, investing a little, avoiding panic, retiring somedayhow hard can it be? Then life walks in wearing muddy boots: taxes, market swings, college bills, insurance decisions, estate planning, job changes, aging parents, and a 401(k) menu with 37 funds that all sound like they were named by a committee trapped in a conference room.
That is where a good investment advisor can help. A strong advisor is not just someone who picks stocks while staring thoughtfully at a monitor. In fact, if your advisor’s entire value proposition is “I know where the market is going,” you may want to keep one hand on your wallet and the other on the exit door. A good investment advisor helps organize your financial life, clarify your goals, manage risk, build an investment strategy, reduce emotional decision-making, and keep your plan moving when life gets noisy.
This article explains what a good investment advisor actually does, how they can add value, what questions to ask before hiring one, and how to know whether the relationship is worth the cost.
What Is an Investment Advisor?
An investment advisor is a financial professional or firm that gives advice about securities, portfolios, and investment strategies. Many advisors also offer broader financial planning services, including retirement planning, tax-aware investing, estate coordination, education planning, insurance review, and cash-flow strategy.
There are different types of financial professionals, and the titles can be confusing. “Financial advisor” is a broad phrase. A registered investment adviser, often called an RIA, generally has a fiduciary duty when giving investment advice. Brokers and dual-registered professionals may operate under different standards depending on the service being provided. This is why one of the first questions to ask is simple: “Will you act as a fiduciary for me at all times?”
A fiduciary advisor must put your interests ahead of their own when giving advice. That does not make every fiduciary brilliant, charming, or immune to bad coffee-fueled decisions, but it does create an important legal and ethical foundation.
What Will a Good Investment Advisor Do for Me?
A good investment advisor helps you make better financial decisions before, during, and after major life events. They bring structure to your money, which is far more useful than random hot tips from a cousin who once “almost bought Apple early.”
1. Help You Define Clear Financial Goals
Before recommending investments, a good advisor should ask questions. Not two questions. Not “How aggressive are you?” followed by a generic pie chart. They should learn about your income, expenses, family situation, debts, goals, timeline, values, concerns, and tolerance for uncertainty.
For example, “I want to retire comfortably” is not a financial plan. It is a wish wearing business casual. A good investment advisor turns that wish into measurable targets: desired retirement age, annual income needs, expected Social Security, pension options, healthcare costs, tax considerations, inflation assumptions, and withdrawal strategy.
The result is a plan you can actually track. Instead of wondering whether you are “doing okay,” you can see whether you are on pace, behind, or aheadand what to adjust next.
2. Build an Investment Strategy That Fits Your Life
A good advisor does not build your portfolio around trends. They build it around your goals, time horizon, cash-flow needs, tax situation, and risk capacity. That usually means choosing an appropriate asset allocation across stocks, bonds, cash, and possibly other investments.
For a 32-year-old investing for retirement, a growth-oriented portfolio may make sense because the time horizon is long. For a 67-year-old who needs monthly withdrawals, the strategy may need more attention to income, stability, liquidity, and sequence-of-returns risk. Same market, different lives, different plans.
A good investment advisor will also help you diversify. Diversification is not glamorous. It will not make your neighbor jealous at a barbecue. But it can help reduce the risk of having too much money tied to one company, sector, country, or idea. In investing, boring often pays rent.
3. Keep You From Making Expensive Emotional Mistakes
One of the most valuable things a good advisor can do is stop you from turning temporary fear into permanent damage. Markets fall. Headlines scream. Your phone sends alerts with the emotional warmth of a fire alarm. In those moments, many investors want to sell first and think later.
A good advisor acts as a behavioral coach. They remind you of the plan, explain what is happening, review whether anything fundamental has changed, and help you avoid panic-selling at the worst possible time. They can also keep you from chasing performance after an investment has already had its big run.
This does not mean “never change anything.” It means changes should be based on strategy, not adrenaline. A good advisor brings a calm voice to a room where the market is throwing chairs.
4. Create a Retirement Income Plan
Saving for retirement is one challenge. Turning savings into income is another. A good investment advisor can help you decide which accounts to draw from, how much to withdraw, how to coordinate Social Security, and how to manage taxes along the way.
For example, retirees may have money in taxable brokerage accounts, traditional IRAs, Roth IRAs, 401(k)s, bank accounts, and annuities. The order of withdrawals can affect taxes, Medicare premiums, required minimum distributions, and how long the portfolio may last. A thoughtful advisor helps make those moving parts work together instead of letting them crash into each other like shopping carts in a windy parking lot.
5. Help You Understand Fees and Investment Costs
Costs matter. A good investment advisor explains what you are paying, how they are compensated, and what you receive in return. Common fee models include a percentage of assets under management, flat fees, hourly fees, project-based fees, subscription fees, or commissions. Some advisors are fee-only, meaning they are paid directly by clients and do not receive commissions for selling products.
No fee model is automatically perfect. What matters is transparency, alignment, and value. If an advisor cannot clearly explain how they are paid, what conflicts of interest may exist, and how their recommendations benefit you, that is not a small red flag. That is a red flag holding a megaphone.
6. Coordinate Tax-Aware Investment Decisions
A good advisor is not necessarily your tax preparer, but they should understand how investment decisions affect taxes. Tax-aware planning may include asset location, tax-loss harvesting, capital gains management, Roth conversion analysis, charitable giving strategies, and retirement account contribution planning.
For instance, some investments may be better suited for tax-advantaged retirement accounts, while others may work well in taxable accounts. Selling a winning investment may create capital gains. Converting a traditional IRA to a Roth IRA may create taxable income now but potential tax benefits later. A good advisor helps you evaluate the trade-offs instead of guessing in April with a shoebox full of documents and regret.
7. Review Your Full Financial Picture
Investment advice should not live in a vacuum. Your portfolio is connected to everything else: debt, emergency savings, insurance, estate documents, employee benefits, business ownership, family responsibilities, and future spending needs.
A strong advisor may ask whether you have enough emergency cash, whether your insurance coverage matches your risks, whether your beneficiaries are updated, whether your estate plan reflects your wishes, and whether your retirement accounts are being used efficiently. They may coordinate with your CPA, estate attorney, or insurance professional when needed.
This broad view matters because a portfolio can look good on paper while the rest of the financial plan quietly leaks water. A good advisor checks the plumbing.
What a Good Investment Advisor Should Not Do
Knowing what an advisor should avoid is just as important as knowing what they should provide.
They Should Not Promise Market-Beating Returns
No ethical advisor can guarantee high returns or predict the market with certainty. If someone says they can consistently beat the market without meaningful risk, ask whether they also own a bridge, a unicorn stable, or a time machine.
They Should Not Push Products Before Understanding You
If the first meeting turns into a sales pitch for an annuity, fund, insurance policy, or private investment before the advisor understands your needs, slow down. Recommendations should follow discovery, not replace it.
They Should Not Hide Conflicts
Conflicts of interest can exist in many business models. The key is whether they are clearly disclosed, managed, and minimized. A good advisor explains conflicts in plain English.
They Should Not Use Jargon as a Smoke Machine
Finance has enough jargon to fill a storage unit. A good advisor makes concepts understandable. If you leave meetings feeling smaller, dumber, or more confused, the advisor may not be communicating well. You are hiring guidance, not a vocabulary ambush.
How an Investment Advisor Adds Value Beyond Picking Investments
Many people assume advisors are useful only if they pick winning investments. That view is too narrow. Investment selection matters, but advisor value often comes from planning, behavior management, tax strategy, disciplined rebalancing, risk control, and better decision-making during important moments.
Consider a family deciding whether to sell company stock, fund a 529 plan, refinance debt, increase retirement contributions, buy a larger home, and help aging parentsall at once. The best investment choice depends on the whole picture. A good advisor helps prioritize decisions and avoid solving one problem by creating three new ones.
Or consider someone nearing retirement during a market decline. A weak plan may lead to panic. A strong plan may include cash reserves, bond allocations, flexible withdrawal rules, and realistic expectations. The advisor’s value is not just in choosing funds. It is in designing a system that helps the investor stay financially and emotionally steady.
Questions to Ask Before Hiring an Investment Advisor
Before hiring an advisor, interview them the way you would interview someone who may influence your future lifestylebecause they might. Helpful questions include:
- Are you a fiduciary at all times when working with me?
- How are you compensated?
- What services are included in your fee?
- What credentials and experience do you have?
- Who is your typical client?
- How will you build and monitor my financial plan?
- How often will we meet?
- What investment philosophy do you follow?
- Do you receive commissions, referral fees, or other incentives?
- Have you or your firm had disciplinary issues?
You can also review an advisor’s Form ADV, Form CRS, and public registration records. These documents can help you understand services, fees, conflicts, disciplinary history, and whether the professional is registered.
When Do You Need an Investment Advisor?
You may benefit from an advisor if your financial life has become too complex, your decisions feel high-stakes, or you simply do not want to manage everything alone. Common moments to seek advice include:
- Starting a serious retirement savings plan
- Changing jobs or evaluating a 401(k) rollover
- Receiving an inheritance
- Selling a business or property
- Preparing for retirement
- Managing concentrated stock positions
- Planning for college costs
- Navigating divorce or widowhood
- Coordinating tax, estate, and investment decisions
You do not need to be wealthy to ask for help. Some people hire advisors for ongoing portfolio management. Others pay for a one-time financial plan, hourly advice, or a second opinion. The right model depends on your needs, budget, and willingness to implement recommendations yourself.
How to Know If Your Advisor Is Doing a Good Job
A good advisor relationship should make your financial life clearer, not more mysterious. You should understand your plan, know what you are paying, and feel comfortable asking questions. Your advisor should update your strategy when your life changes and help you stay disciplined when markets get uncomfortable.
Signs of a good advisor include clear communication, written planning, transparent fees, regular reviews, personalized recommendations, realistic expectations, and a willingness to explain both benefits and risks. They should be proactive without being pushy and confident without pretending to be psychic.
Performance matters, but it should be evaluated against appropriate benchmarks, your goals, your risk level, and your time horizon. A conservative portfolio should not be judged against a roaring stock index. A retirement income strategy should not be judged only by one-year returns. Context matters.
Real-Life Examples of Advisor Value
The Nervous Investor During a Market Drop
Imagine an investor with $600,000 saved for retirement. The market drops sharply, and they want to sell everything. A good advisor reviews the plan, shows how the portfolio was built for downturns, discusses cash needs, and helps the client avoid locking in losses unnecessarily. The value is not a magic trade. It is preventing a fear-based decision that could damage years of progress.
The Couple Five Years From Retirement
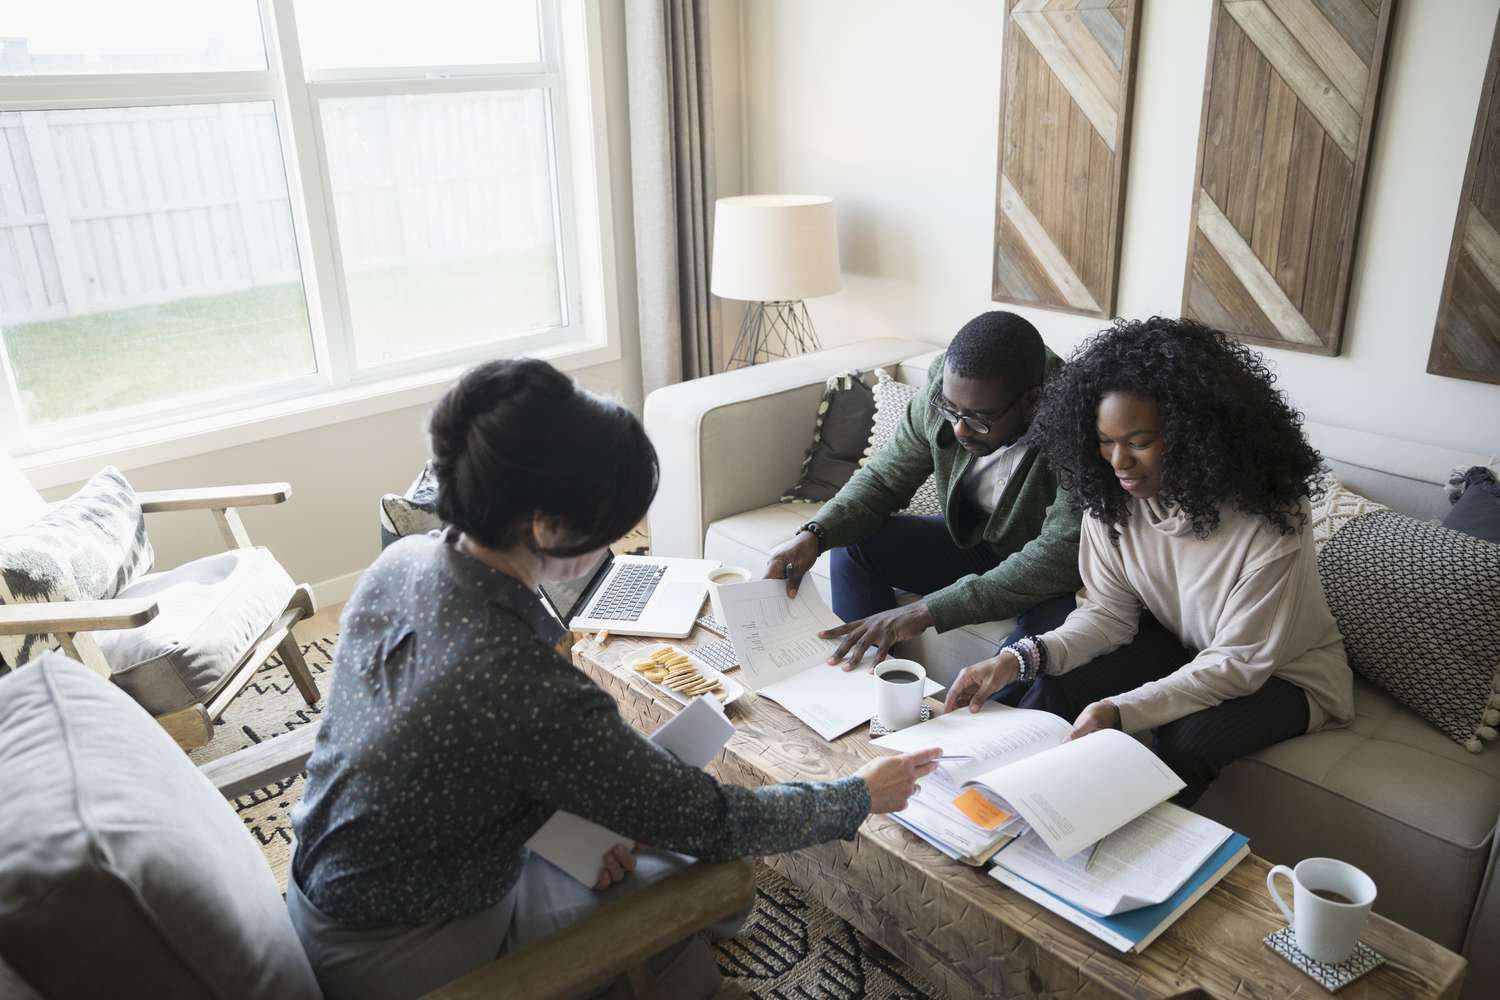
A couple nearing retirement has a 401(k), two IRAs, a taxable account, a mortgage, and questions about Social Security. A good advisor helps estimate retirement spending, model different claiming ages, rebalance investments, create a withdrawal strategy, and coordinate with a tax professional. Instead of guessing, the couple gets a roadmap.
The High Earner With Too Much Cash
A professional earns a strong income but keeps most savings in cash because investing feels intimidating. A good advisor helps create an emergency fund, invest excess cash gradually, use retirement accounts efficiently, and build confidence. The advisor’s job is part planner, part educator, and part financial personal trainerminus the burpees.
Experiences Related to “What Will a Good Investment Advisor Do for Me?”
In real life, the value of a good investment advisor often shows up in moments that do not look dramatic from the outside. It may not be a dazzling stock pick or a thrilling market call. More often, it is a quiet decision made correctly: staying invested during volatility, increasing retirement contributions, avoiding an unsuitable product, updating beneficiaries, or choosing a tax-smart withdrawal strategy.
One common experience is the “financial junk drawer” problem. Many people collect accounts over time: an old 401(k), a newer 401(k), a Roth IRA opened years ago, a brokerage account, a savings account, maybe a few individual stocks, and possibly a forgotten account from an employer whose logo has changed twice. Nothing is necessarily wrong, but nothing is coordinated. A good advisor helps organize the pieces. They identify overlap, reduce unnecessary complexity, and make sure each account has a purpose.
Another experience involves couples who think they agree about money until retirement planning begins. One person may want security, while the other wants growth. One may want to retire early, while the other worries about healthcare. A good investment advisor can turn those emotional conversations into practical planning discussions. Instead of arguing about vague fears, the couple can review numbers, scenarios, and trade-offs. The advisor becomes a translator between dreams and spreadsheets.
Business owners often have a different experience. Their wealth may be tied up in the company, making their personal financial life less diversified than it appears. A good advisor may help separate business cash from personal reserves, plan for taxes, create retirement savings outside the business, and prepare for a possible sale or succession. This is especially important because entrepreneurs are often excellent at taking business risks but less disciplined about personal risk management.
Another powerful experience comes after a major life change. Divorce, widowhood, inheritance, job loss, or the birth of a child can make financial decisions feel urgent and emotional. A good advisor slows the process down. They help identify what must be handled immediately, what can wait, and what should not be decided under stress. Sometimes the best advice is not “buy this” or “sell that.” Sometimes it is, “Let’s not make a permanent decision during the hardest month of your life.”
Many investors also discover that a good advisor improves confidence. Not overconfidencethe dangerous kind that makes people trade options after watching two online videosbut grounded confidence. They understand why they own what they own. They know how much risk they are taking. They know when the plan will be reviewed. They know what to do when markets fall. That clarity can reduce financial anxiety, which is not a line item on a statement but absolutely matters.
Finally, a good advisor helps people connect money to meaning. The real goal is rarely “maximize portfolio efficiency.” The goal is to retire with dignity, help children without spoiling them, support causes, care for family, travel, start a business, or sleep better at night. A good investment advisor keeps the portfolio connected to the life it is supposed to support.
Conclusion
A good investment advisor does much more than recommend funds or watch the market. They help you define goals, build a personalized investment strategy, manage risk, plan for retirement income, understand fees, reduce tax surprises, avoid emotional mistakes, and coordinate your financial life. The best advisors bring clarity, discipline, and perspectivethree things that become especially valuable when life gets complicated or markets get loud.
Hiring an investment advisor is not about handing over your brain or hoping someone can predict the future. It is about building a professional relationship that helps you make smarter decisions with your money. The right advisor should educate you, challenge you when needed, explain trade-offs clearly, and keep your plan aligned with your real life.
In other words, a good investment advisor will not promise you a yacht by Tuesday. But they can help you avoid costly mistakes, use your resources wisely, and move toward your financial goals with a lot more confidenceand possibly fewer late-night searches for “Is the stock market mad at me?”