Project delays are the uninvited dinner guests of construction. They show up late, eat the budget, complain about the schedule, and somehow leave everyone arguing over who invited them. For contractors, developers, property owners, lenders, and insurance agents, a delay is rarely just “extra time.” It can mean extra rent, loan interest, crane rentals, re-inspection fees, legal bills, expediting costs, additional project management, missed income, and a very nervous owner staring at a spreadsheet like it personally betrayed them.
The phrase extra expense exposure sounds simple, but in insurance it can become tricky fast. A standard builder’s risk policy may repair damaged property, but that does not automatically mean it will pay every cost caused by a delayed opening or delayed completion. In many cases, delay-related costs must be specifically addressed through endorsements such as soft costs coverage, delay-in-completion coverage, delay in start-up coverage, or, for specialized equipment and installation work, an installation floater.
This article breaks down how project delays create extra expense exposure, why standard coverage can fall short, and how insurance professionals and project stakeholders can solve the problem before a crane, custom HVAC unit, storm, fire, or supply-chain hiccup turns the schedule into confetti.
What Is Extra Expense Exposure in a Project Delay?
Extra expense exposure is the financial hit a business takes when it must spend more than expected because a project cannot finish on time. In construction and installation work, those expenses may appear in dozens of places. Some are obvious, such as overtime labor or rush shipping. Others hide in the corners like raccoons in a job trailer: extra interest on construction loans, revised architectural drawings, extended equipment rental, taxes, insurance premiums, security, temporary utilities, and advertising to announce a new opening date.
The problem is that project stakeholders often assume these expenses are naturally covered because they feel connected to the loss. Unfortunately, insurance policies do not operate on vibes. They operate on triggers, definitions, exclusions, limits, waiting periods, and named insured language. That means a loss may feel covered emotionally while being excluded technically. And technical exclusions have never cared about anyone’s feelings.
In many project-delay scenarios, the first question is not “Did the project lose money?” The better question is: What caused the delay? If the delay was caused by covered physical damage, such as fire, wind, theft, vandalism, collapse, or another insured peril, a builder’s risk policy may respond to repair the damaged property. But the extra costs caused by the delay may require separate coverage.
Why Builder’s Risk Alone May Not Be Enough
Builder’s risk insurance is designed to protect buildings, materials, supplies, and equipment while construction is underway. It is property coverage for a project before the project becomes a completed building. It can be essential, but it is not a magical construction wallet.
Most builder’s risk policies focus first on direct physical loss or damage. If a fire damages framing, the policy may pay to repair or replace the damaged property, subject to its terms. But if that fire also delays the opening of a restaurant by three months, the restaurant owner may face lost revenue, extra advertising, loan interest, and extended professional fees. Those costs do not automatically fit under basic property damage coverage.
That is where soft costs and delay-in-completion coverage enter the chat. Soft costs are expenses indirectly related to the construction project, not the bricks, beams, wiring, or concrete themselves. Common examples include architectural fees, engineering fees, legal fees, accounting costs, permit fees, loan interest, real estate taxes, insurance premiums, marketing expenses, and project management costs.
Delay-in-completion coverage, sometimes called delay in start-up, delayed opening, soft costs, or advance loss of profits coverage, is designed to address income loss or specified additional expenses caused by a covered delay. The key word is specified. If the expense is not listed, defined, or endorsed, there may be no recovery. Insurance is not a buffet where the insured grabs whatever looks expensive.
The IA Magazine Problem: When the Exposure Is Real but the Form Is Hard to Find
The insurance challenge highlighted by the IA Magazine discussion is familiar: a client wants protection from extra expenses caused by a potential project delay, but standard builder’s risk forms may not clearly provide the needed coverage. The example involved a specialized HVAC unit, project timing, delivery, installation, and the question of whether extra costs associated with delay could be insured.
That scenario is a perfect reminder that the correct insurance solution depends on the facts. Is the insured responsible for the equipment while it is in transit? Is the property being installed? Is the exposure tied to physical damage to the unit? Is the delay caused by damage, late delivery, a transportation issue, weather, crane availability, or a contractual penalty? Is the insured the contractor, project owner, building owner, or supplier?
For some specialized installation jobs, an installation floater may be more appropriate than relying only on builder’s risk. An installation floater is an inland marine policy used to cover materials, equipment, and supplies during transit, temporary storage, and installation. It is especially useful for subcontractors and specialty trades such as HVAC, electrical, plumbing, communications, or other contractors bringing valuable equipment to a job site.
However, even an installation floater must be reviewed carefully. The policy should describe the covered property, covered perils, transit exposure, testing exposure, off-site storage, temporary locations, and any delay-related coverage. If the insured is worried about extra expense that does not result from direct physical damage, the standard market may not offer a clean answer, and a surplus lines solution may be needed.
Common Coverage Gaps That Turn Delays Into Disputes
1. No Covered Physical Damage Trigger
Many delay coverages require a covered physical loss before soft costs or extra expenses are triggered. If a project is delayed because of poor scheduling, permit issues, labor shortages, design revisions, financing problems, or ordinary late delivery, insurance may not respond. Those are business risks, not necessarily insured property losses.
2. The Wrong Party Is Named
One of the most painful coverage surprises occurs when the project owner assumes it has delay coverage but is not the named insured for that section of the policy. Builder’s risk policies often include owners, contractors, and subcontractors for property damage interests, but delay coverage may apply only to a specific named insured. If the owner needs loss of rents, business income, or soft costs coverage, the owner’s status must be unmistakable.
3. Soft Costs Are Not Itemized
Soft costs coverage usually does not mean “all soft costs known to humankind.” It often covers only the categories listed in the policy or declarations. If extended general conditions, developer overhead, equipment rental, re-leasing expenses, or tax-credit impacts are not listed, the insured may be left arguing after the loss. Arguing after a loss is expensive, slow, and about as fun as reading policy definitions during a power outage.
4. The Waiting Period Eats the Claim
Delay coverage often includes a time deductible or waiting period, such as 14, 30, or 60 days. Costs incurred during that period may not be covered. A short delay can still be financially painful but fall below the policy’s threshold.
5. The Delay Period Is Misunderstood
The delay period often begins on the anticipated completion date and ends when the project is actually completed, subject to policy language. This can create disputes when the project was already behind schedule before the covered loss, or when non-loss factors contribute to the final delay. Accurate scheduling records are critical.
6. Contracts Transfer Risk Poorly
Insurance cannot fix every bad contract. If the construction agreement, supply contract, crane contract, delivery contract, or lease assigns delay responsibility to the insured, the insurance program must match that obligation. Otherwise, the client may have promised to absorb costs that no policy was designed to pay.
How to Solve the Extra Expense Exposure Before the Project Starts
Step 1: Map the Real Delay Scenario
Do not start with the policy. Start with the project. What could delay completion? Custom equipment? Weather? Transit? Testing failure? Utility connection? Permitting? A single imported component? A helicopter lift? A specialized subcontractor with a calendar tighter than a parking space in Manhattan?
Once the delay scenarios are mapped, separate them into insurable and non-insurable categories. A fire damaging stored materials is different from a supplier simply missing a deadline. Physical damage is different from poor planning. A covered peril is different from a contractual penalty.
Step 2: Identify Every Party With a Financial Interest
The owner may face lost rents or lost business income. The contractor may face extended general conditions. The subcontractor may face equipment replacement and remobilization costs. The lender may care about debt service. The tenant may care about opening-day revenue. Each party’s exposure should be listed separately.
This matters because one policy may not protect everyone in the same way. Builder’s risk may cover property interests broadly, while delay coverage may protect only named parties. When in doubt, spell it out. Insurance policies reward clarity and punish assumptions.
Step 3: Choose the Right Coverage Combination
A strong solution may include several parts:
- Builder’s risk insurance for direct physical loss to the project during construction.
- Soft costs coverage for itemized delay-related expenses such as interest, fees, taxes, insurance, and professional costs.
- Delay-in-completion or delay in start-up coverage for lost rental income, business income, or gross earnings caused by a covered delay.
- Extra expense coverage for acceleration costs, temporary measures, or additional costs needed to reduce the delay.
- Installation floater coverage for materials or equipment in transit, storage, testing, and installation.
- Contractual risk transfer through indemnity provisions, delivery obligations, liquidated damages clauses, and insurance requirements.
Step 4: Itemize Soft Costs Like a Forensic Accountant With Coffee
Do not simply request “soft costs.” Build a schedule of potential expenses. Include loan interest, real estate taxes, insurance premiums, legal fees, accounting fees, architectural and engineering fees, permit fees, re-inspection costs, marketing expenses, leasing expenses, contractor general conditions, developer overhead, equipment rental, temporary utilities, security, and professional consultants.
Then assign realistic limits. A $50 million project with a $25,000 soft costs sublimit is not a risk management strategy; it is a decorative sticker.
Step 5: Confirm the Delay Trigger
Ask whether coverage applies only after direct physical loss or damage to covered property. If the insured needs coverage for delay without physical damage, that must be discussed upfront. Standard forms may not offer it, and specialty or manuscript coverage may be required.
Step 6: Align Insurance With the Construction Contract
The insurance requirements in the contract should match the actual policy. If the contract requires delay-in-completion coverage for the owner, the owner should be properly named. If the contractor needs extended general conditions covered, those costs should be included in the soft costs schedule. If a supplier is responsible for late delivery, the contract should state remedies clearly.
Step 7: Keep the Schedule Honest
Delay claims are schedule claims wearing an insurance hat. The insured must be able to show the planned completion date, the actual completion date, the cause of the delay, and how much delay was attributable to the covered loss. Updated schedules, daily reports, photos, change orders, delivery logs, meeting minutes, and correspondence can make or break the claim.
Example: The HVAC Unit That Delays the Whole Building
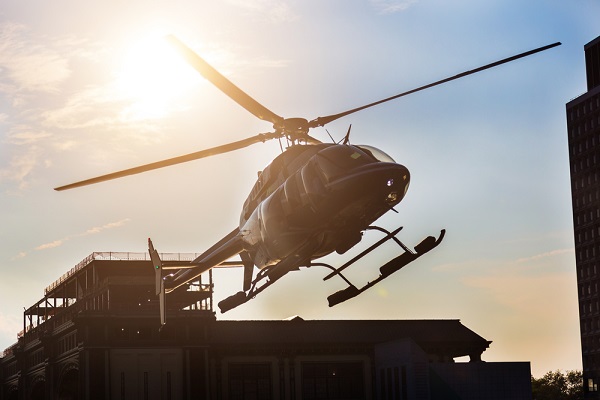
Imagine a commercial property that needs a custom HVAC unit installed by crane or helicopter. The unit is expensive, the delivery window is narrow, and the building cannot receive final occupancy approval without it. The owner expects tenants to move in on July 1. The contractor has crews scheduled. Marketing has already announced the opening date. Everyone is smiling. This is usually when construction comedy begins.
If the HVAC unit is damaged in transit by a covered peril, an installation floater may cover the physical damage to the unit, depending on policy terms. But what about the extra cost to rush a replacement? What about the helicopter service cancellation fee? What about tenant concessions, extra loan interest, revised inspections, and additional project management?
The answer depends on the coverage. If the policy includes extra expense, expediting expense, soft costs, or delay-in-completion coverage that applies to the insured and the loss, some of those expenses may be recoverable. If the policy covers only direct physical damage to the unit, the insured may receive money for the damaged equipment but not the financial chain reaction that follows.
This is why the insurance conversation must happen before the project begins. By the time the helicopter is grounded and the owner is asking whether “delay pain” is a covered category, it is probably too late.
Practical Risk Management Tips for Agents, Owners, and Contractors
First, review the entire construction ecosystem. A project is not just a job site; it is a network of contracts, suppliers, lenders, tenants, permits, equipment, weather, schedules, inspections, and human beings who occasionally forget to reply-all.
Second, request policy forms and endorsements early. Do not rely on proposal summaries. Summaries are helpful, but the policy language controls. Review definitions of covered property, covered causes of loss, soft costs, extra expense, delay period, waiting period, named insured, and exclusions.
Third, build a delay-cost worksheet. Estimate the monthly cost of a delayed opening. Include fixed costs, variable costs, financing costs, professional fees, lost income, acceleration costs, and contractual penalties. Then compare that number to the policy limit. If the limit would disappear faster than pizza at a subcontractor meeting, increase it.
Fourth, coordinate builder’s risk with permanent property coverage. Phased occupancy can create gaps. If part of a building becomes operational while another section remains under construction, the transition between construction coverage and permanent property coverage must be handled carefully.
Fifth, document everything. When a claim occurs, the best evidence is not a dramatic email written six weeks later. It is the boring daily report, the baseline schedule, the updated schedule, the delivery record, the change order, the invoice, and the meeting note that proves what happened.
Experience Section: Lessons Learned From Real-World Project Delay Problems
In practical insurance work, project delay problems often begin with a sentence that sounds harmless: “We’re only running a little behind.” That little delay can become a large exposure when the project has a financing deadline, a tenant move-in date, a seasonal opening, or a contract with liquidated damages. A delayed apartment complex may lose rent. A delayed hotel may miss tourist season. A delayed medical office may postpone revenue. A delayed restaurant may have staff hired, food-service contracts ready, and advertising already paid for. The calendar becomes a cash register, and every missed day makes noise.
One useful experience is to treat every project schedule like a financial document, not just an operations tool. Owners often focus on construction value because it is easy to see: labor, materials, steel, concrete, mechanical systems, finishes. But the hidden cost of time can be just as important. When a project delay occurs, the owner may continue paying interest, taxes, insurance, consultants, legal bills, and staff costs even though no revenue is coming in. Those expenses do not look dramatic individually, but together they can behave like a slow leak under a finished floor.
Another lesson is that specialty equipment deserves special attention. HVAC systems, elevators, switchgear, generators, medical equipment, refrigeration units, and custom building components can become schedule-critical items. If one item is damaged, lost, delayed, or fails testing, the entire project may stop. The insurance review should ask where the item will be manufactured, who owns it during transit, who is responsible during storage, who installs it, whether testing is covered, and what happens if the component must be expedited or replaced.
A third lesson is that contracts and insurance must speak the same language. Many disputes happen because the construction contract requires one thing while the insurance policy provides another. The contract may require the contractor to carry coverage for delay, but the policy may protect only the owner’s soft costs. Or the owner may assume rental income is covered, but the policy names only the contractor for the relevant time-element endorsement. These mismatches are avoidable, but only if someone compares the contract to the policy before the loss.
Finally, the best claims outcomes usually come from boring discipline. A clean baseline schedule, consistent updates, clear cost codes, saved invoices, documented change orders, and prompt notice to the carrier can do more for recovery than a long emotional explanation after the fact. Insurance companies need proof. Courts need proof. Adjusters need proof. Your future self also needs proof, because six months into a delay, nobody remembers exactly what happened on Tuesday at 2:15 p.m. except the project manager who wrote it down.
Conclusion: Solve the Exposure Before the Delay Solves Your Budget
Project delays are not always avoidable, but uncovered extra expenses often are. The solution is not to assume that builder’s risk, business income, or extra expense language will automatically protect every financial consequence of a delayed project. The solution is to identify the exposure, connect it to the correct coverage, name the correct insureds, itemize the correct soft costs, choose realistic limits, and align the policy with the contracts.
For insurance agents, the opportunity is consultative. Ask better questions. Review the project timeline. Find the bottlenecks. Examine who pays if the project is late. For owners and contractors, the takeaway is equally simple: do not wait until a loss occurs to learn whether delay costs are covered. At that point, the policy language has already been written, the schedule has already slipped, and the budget may already be making tiny screaming sounds.
Note: This article is original editorial content based on insurance and construction-risk research. Coverage varies by policy, carrier, jurisdiction, and project facts, so readers should consult a licensed insurance professional, attorney, or qualified risk adviser before making coverage decisions.